For some time now, you have likely heard us talk about our Portfolio Managers’ (PM) affinity for the 20-year spot on the yield curve. This year, however, you may have noticed that longer maturities have been a drag on performance year-to-date. Despite this volatility, we remain convinced in the value offered by the 20-year Treasury; in fact, we have continued adding to the position. In this article, we explain why.
There are two key reasons behind our conviction. The first is the power of higher starting income, which our Client Portfolio Manager, Taylor Huffman, covered in the June installment of “Shape of the Markets.” The second is how attractive the 20-year Treasury looks today, relative to everything else in the fixed income market.
As a quick recap on the power of starting income: in August 2021, it would have taken only a small increase in rates to move the 20-year Treasury into negative territory1. Today, rates on the 20-year Treasury would need to rise by over 180 basis points (bps) over three years before this bond faces a negative annualized return2. This is why you’ll hear us say, “the higher rates go, the safer bonds get.” On the flip side, if rates fall by roughly 100 bps over the next three years, the 20-year Treasury’s Annual Return would equal the 20-year historic average of the S&P 500 Index3 (9.24%)! As a stand-alone investment, the 20-year Treasury has an attractive, go-forward return profile.
Three-year horizon total return analysis (Illustrative performance)
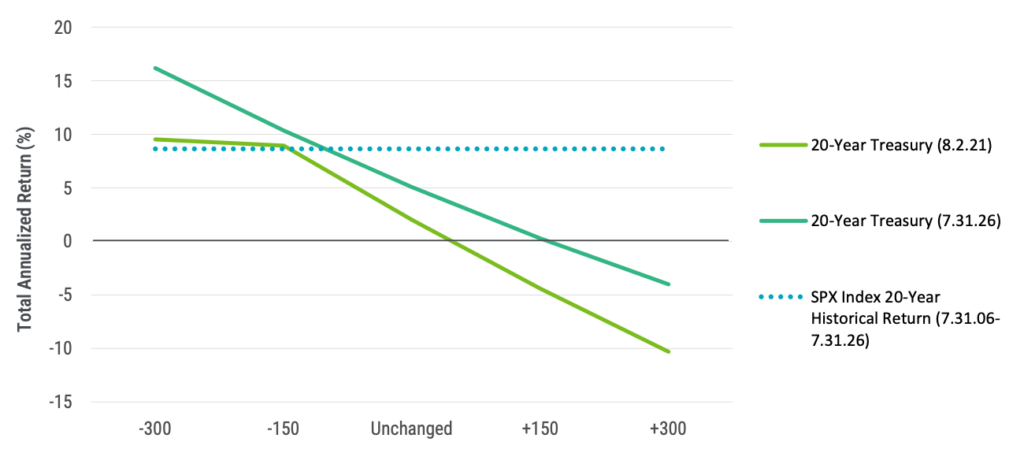
Change in Interest Rates (Basis Points)
Sources: PTAM, Bloomberg. The 20-Year Treasury is constructed with the on-the-run 20-Year Treasury, but broadly speaking, could be a Treasury with a tenor between 15 and 25 years. These total returns are estimated over a 3-year horizon. The following bonds that are used to create the Shapes are held by PTAM clients as of the date of this presentation: 20-year Treasury.
Assumptions: (1) a parallel shift in the yield curve (2) static allocation for 3 years (3) linear rate changes (4) sector specific spreads are held constant across five rate scenarios (5) reinvestment rate consistent with respective sector.
High levels of starting income are important, but they don’t capture the whole story. For example, in October of 2023, the yield on a 20-year Treasury was higher than it is now; however, the 20-year Treasury is a better choice for portfolios today than it was in 2023. Why does this sector make more sense for investors now?
1) Slope- If we look at the differences between the 2023 yield curve and today’s curve, we can see that the overall steepness of today’s yield curve is greater than it was in 2023. Back then, the level of compensation received for shorter-term Treasuries rivaled that of the 20-year Treasury. The break-even between shorter and longer bonds was far less attractive than it is today, and this is why, in 2023, we held a larger proportion of “Defensive” sectors, relative to our “Offense.” Over the last three years, the short end of the yield curve has fallen over 150 bps. This significantly changes the relative value equation between long and short bonds. For example, on October 19th of 2023, when the 20-year
Treasury offered a 5.34% yield, the 3-year horizon, rates-unchanged scenario, total return was 5.59%4 for the 20-year Treasury, and 5.52%4 for the 1-year Treasury. In 2023, only 7 bps of total return separated the 1- and 20-year Treasury. Today, the 20-year Treasury offers a 3-year horizon, rates- unchanged total return of 5.82%5, while the 1-year Treasury only offers 4.00%5; that’s over 180 bps of additional return today. Past performance is not indicative of future results.
Three-year horizon total return analysis (Illustrative performance)
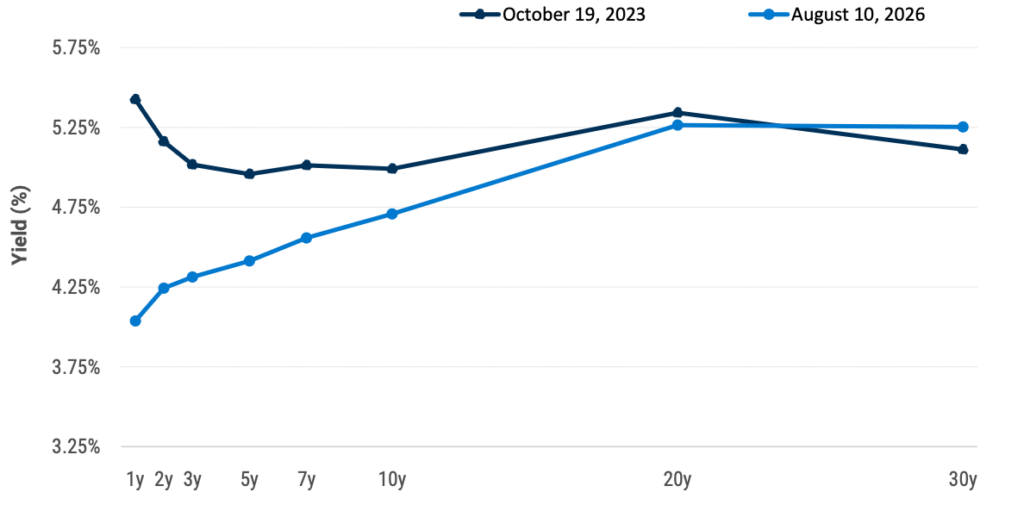
Source: Bloomberg.
2) Spread- If we observe Credit Spreads in October of 2023, both in the Investment Grade (IG) and High Yield (HY) space, investors were being better compensated for credit risk than they are today. On October 19th, when the 20-Year Treasury hit a 5.34% yield, the IG Corporate Option Adjusted Spreads (OAS) Index was at 129 bps6, and the HY Corporate OAS Index was at 423 bps7. In contrast, outside of a few sectors of the market (Commercial Mortgage-Backed Securities and certain Taxable Munis), spreads today are at historically tight levels, with IG and HY Corporate OAS Indices at 78 bps6 and 279 bps7, respectively. When bonds with a credit-risk component experience spread compression, their go- forward return profiles look less attractive, relative to bonds without credit risk. Our senior PM, Mike Plaiss, says it best, “when spreads are tight, Treasuries are cheap.”
What separates the 20-year Treasury of today from the 20-year Treasury of 2023 is its superior relative value when compared to the rest of today’s Fixed Income market. Even so, the 20-year Treasury being more attractive than it has been in over 20 years doesn’t mean it’s the only thing we are buying: given the volatility that comes with longer maturities, we continue to pair longer, low-credit-risk bonds like the 20-year Treasury with shorter bonds where we can take on a bit more credit risk. In this way, we continue to maintain a balanced profile regarding interest rate sensitivity, while simultaneously freeing ourselves to invest in the spots of the curve that offer the most value today.
It should be noted that this strategy is nothing new to PTAM, nor are its benefits. It has contributed to long-term outperformance for our strategies across multiple market environments, with uncertainty and volatility throughout them all. As time passes, short term volatility is moderated, and eventually overcome, when you invest with discipline in assets that win more often than they lose.
1- 20-year Treasury shape as of 8.2.21
2- 20-year Treasury shape as of 7.31.26
3- SPX Index | Historical Returns run in Bloomberg TRA screen, 7.31.06 – 7.31.26
4- 20- and 1-year Treasury shapes as of 10.19.23
5- 20- and 1-year Treasury shapes as of 7.31.26
6- LUACOAS Index – spread data taken from Bloomberg, 10.19.23 – 7.31.26
7- LF98OAS Index – spread data taken from Bloomberg, 10.19.23 – 7.31.26
Adam is a Client Portfolio Manager with 9 years of experience in fixed income markets. He serves as a liaison between the investment, marketing, and sales teams, leading investment strategy updates, portfolio communications, and market commentary. A previous employee of PTAM’s affiliate company, Performance Trust Capital Partners, Adam specializes in educating investors on complex fixed income asset classes and strategies through the lens of Shape Management. He holds a BA in Business Economics from Wheaton College.
Glossary
Yield Curve refers to the U.S. Treasury yield curve rates.Risks and Other Important Considerations
Investing involves risk; principal loss is possible. Investments in debt securities typically decrease in value when interest rates rise. This risk is usually greater for longer-term debt securities. Investments in lower rated and non-rated securities present a greater risk of loss to principal and interest than higher-rated securities. Investments in asset-backed and mortgage-backed securities include risks that investors should be aware of such as credit risk, prepayment risk, possible illiquidity and default, as well as increased susceptibility to adverse economic developments. For a complete list of disclosures, please visit [www.ptam.com](https://www.ptam.com). When selecting a bond to invest in, most investors rely on what we refer to as “traditional fixed income metrics,” which are generally a combination of (1) taking a stance on whether interest rates will increase or decrease, (2) yield and (3) duration. Nearly 30 years ago, PTAM’s founders recognized the potential shortcomings in traditional bond metrics, and developed Shape Management, a math-based investment process that addresses each of these shortcomings by analyzing the risk return profile of a bond’s future cash flows. Shape Management is a mathematical calculation that analyzes the risk return profile of a bond’s or group of bonds’ future cash flows. By using Shape Management, PTAM creates projections of the performance of specific bonds or grouping of bonds. These projections are not the actual performance of any bond or product. As a result, Shape Management performance in this email were not actually achieved by any PTAM investment or product. The criteria and assumptions underlying the projected performance may prove to be incorrect. Prospective investors should not rely solely on such projected performance and should conduct a thorough independent analysis of the investment opportunity. The graphs included throughout this email are provided for illustrative and educational purposes only. Projected performance results may have many inherent limitations. No representation is being made that an investment will, or is likely to, achieve profits or losses similar to those shown. In fact, there are frequently significant differences between projected performance results and actual results subsequently achieved. Although projected performance may be useful to consider when making an investment decision. Investment decisions based on Shape Management information may not be profitable. All projected performance is shown as net performance, which includes management fees, reinvestment of interest payments, principal payments, and capital gains. The information included is not an offer, recommendation or professional advice. Certain information contained herein has been obtained from third party sources and such information has not been independently verified by PT Asset Management, LLC. No representation, warranty, or undertaking, expressed or implied, is given to the accuracy or completeness of such information by PT Asset Management, LLC or any other person. While such sources are believed to be reliable, PT Asset Management, LLC does not assume any responsibility for the accuracy or completeness of such information. PT Asset Management, LLC does not undertake any obligation to update the information contained herein as of any future date. This email is confidential, is intended only for the person to whom it has been directly provided and under no circumstances may a copy be shown, copied, transmitted or otherwise be given to any person other than the authorized recipient without the prior written consent of PT Asset Management, LLC. Any indices and other financial benchmarks shown are provided for illustrative purposes only, are unmanaged, reflect reinvestment of income and dividends and do not reflect the impact of advisory fees. Investors cannot invest directly in an index. Comparisons to indexes have limitations because indexes have volatility and other material characteristics that may differ from a particular hedge fund. For example, a hedge fund may typically hold substantially fewer securities than are contained in an index. Certain information contained herein constitutes “forward-looking statements,” which can be identified by the use of forward-looking terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” or “believe,” or the negatives thereof or other variations thereon or comparable terminology. Due to various risks and uncertainties, actual events, results or actual performance may differ materially from those reflected or contemplated in such forward-looking statements. Nothing contained herein may be relied upon as a guarantee, promise, assurance or a representation as to the future.Investment and Insurance Products: •Are not FDIC or any other Government Agency Insured •Are not Bank Guaranteed •May Lose Value
Financial Professionals Only. Not for public distribution.© 2026 PT Asset Management, LLC. All Rights Reserved. PT Asset Management, LLC (“PTAM”) is the advisor to the PTAM Funds. Distributed by ALPS Distributors, Inc.
The Fund’s investment objectives, risks, charges and expenses must be considered carefully before investing. The summary and statutory prospectuses contain this and other important information about the investment company, and may be obtained by calling 1.877.738.9095. Read carefully before investing.